Organizing Receipts for Tax Records
Business receipts are most useful when they identify what was purchased, when, from whom and why it belongs to the business. An orderly receipt process connects that supporting document to the recorded transaction, including purchases paid in cash. Digital copies can work when they satisfy recordkeeping requirements, but simply taking a blurry photo does not guarantee that the record is complete or accessible.
Capture the reason for the purchase
A bank statement can show that money went to a retailer, but not necessarily what the business bought. A purchase from a hardware store might be job materials, tools, office supplies or a personal item. The IRS explains that supporting documents help substantiate transactions and that proof of payment alone does not establish entitlement to a deduction. A practical record should include the merchant, date, amount and description of the item or service, along with enough context to identify the business purpose.
Organize receipts as transactions occur
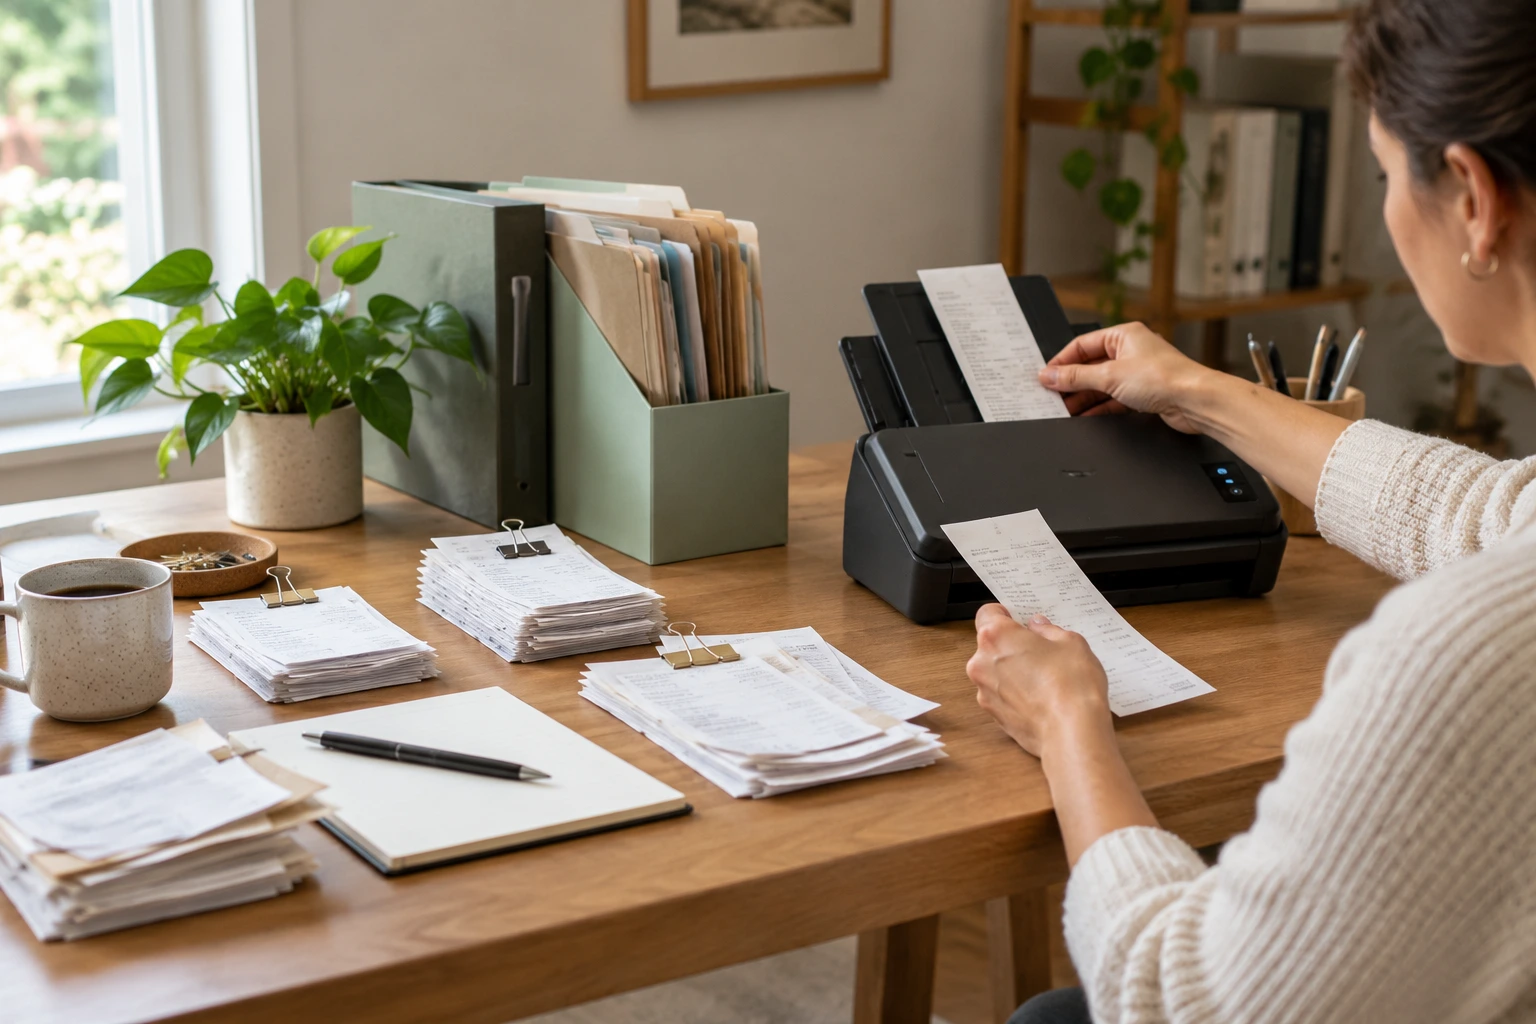
Waiting until the end of the year creates a search across email, vehicles, drawers and payment applications. A more dependable practice is to capture the document when it arrives and assign it to an appropriate category or project reference. The precise method can vary. Some businesses use folders by year and month, others connect receipts directly to accounting software. The system should be consistent and understandable to the people who must maintain it, rather than complicated enough that staff avoid using it.
Cash receipts deserve deliberate attention
Cash purchases may never create a bank or credit card transaction that helps reconstruct the details later. A business should retain the receipt and record the business reason promptly. If a receipt is unavailable, the owner should document the circumstances according to its professional adviser's guidance and applicable rules rather than fabricate a replacement. The tax treatment of an expense is a separate question from whether the purchase can be found in the bookkeeping records.
Digital copies need to be legible and retrievable
The IRS explains that electronic storage systems for tax books and records must preserve complete, accurate and accessible information. A file that cannot be opened, is too blurry to read or lacks the supporting details may not be useful. Scanning apps can help capture thermal-paper receipts before they fade, but owners should check the image and organize it reliably. Backups, access control and a consistent naming method protect against loss and help a business respond when a record is requested years later.
Keep records for the relevant period
Different tax records may have different retention requirements. The IRS provides general limitation periods and identifies exceptions. Businesses should not destroy documents solely because a calendar year ended or because the transaction is already entered in accounting software. Ownership records, assets, payroll information and items involved in an audit can require different treatment. A recordkeeping policy should reflect the applicable category and advice from the appropriate tax professional.
Receipt organization supports usable books
Paper Trail's existing Tax Ready Bookkeeping and Monthly Bookkeeping pages describe the approved service options. Organized source documents help records remain understandable for reviews and tax preparation, but Paper Trail's bookkeeping work should not be represented as tax advice. Use the existing Packages or native quote selection page to discuss the recordkeeping support needed.