Past Due Bookkeeping
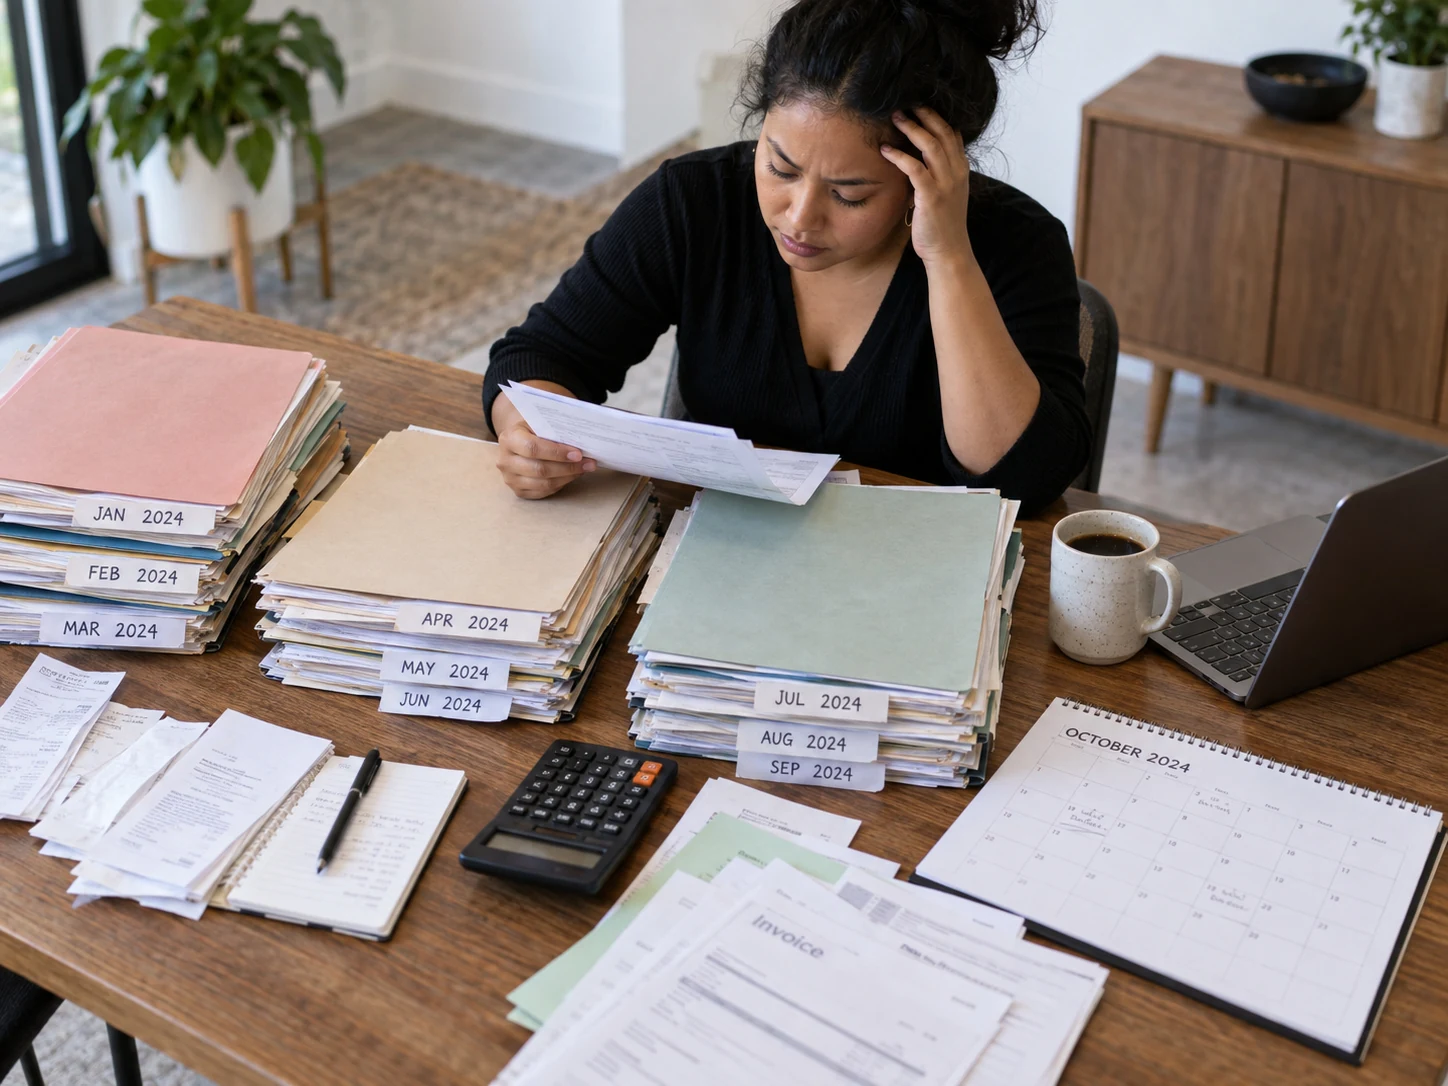
A few unfinished months can turn into a year before you realize it. Start by finding what is missing, what is already reliable and which period needs attention first.
Past Due Bookkeeping Scope
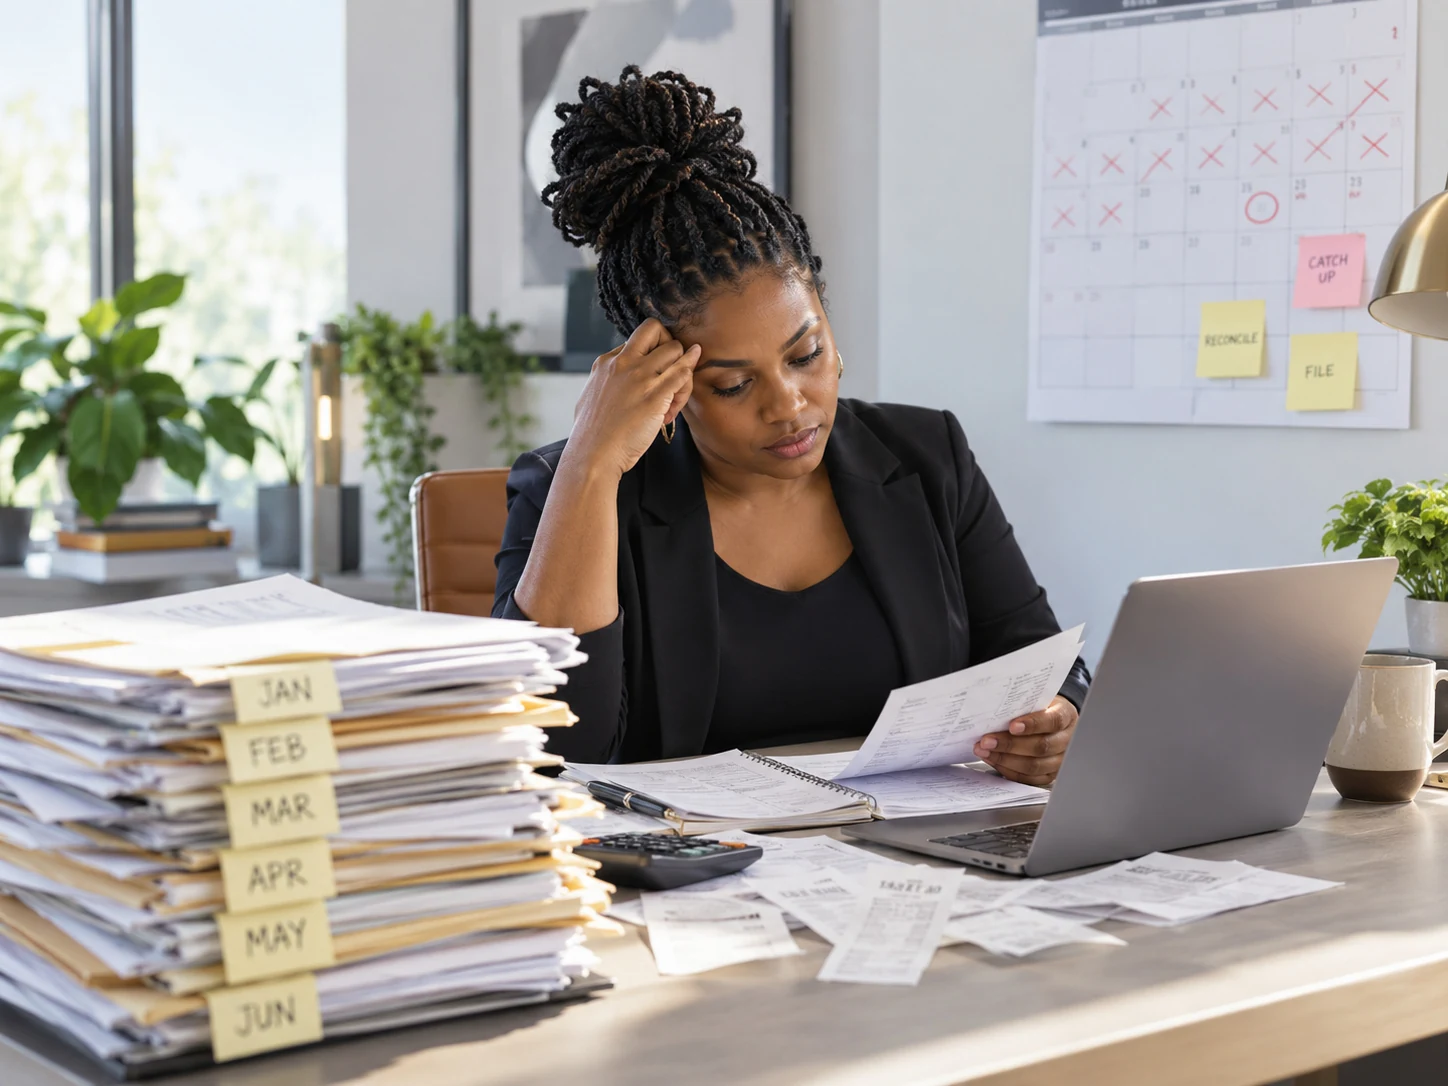
Catch up bookkeeping, also called past due bookkeeping, brings incomplete business records up to an agreed date. The work usually includes collecting historical activity, recording missing transactions, reviewing categories and reconciling accounts month by month. Paper Trail approaches the backlog as a sequence of periods, so the ending point of one month supports the beginning of the next.
Past Due Bookkeeping Services
Records Inventory
The first task is to identify the earliest unfinished period and every business account that was active during it. An account closed six months ago still matters if it held transactions in the period being reviewed. Payment platforms, business credit cards and loan activity may also help explain what appears in the main checking account.
A backlog map separates missing statements, unrecorded activity and entries that exist but have not been reviewed. These are different jobs and should be visible in the scope.
Opening Balances
A recent bank balance cannot explain several months of unfinished books on its own. Catch up work needs a dependable starting point, often the last completed reconciliation or a prior accountant prepared balance. If that starting point contains an error, it may need attention before later months can be completed with confidence.
This is why working from the oldest relevant period forward is often more useful than categorizing the newest transactions first. Earlier errors can otherwise carry through the entire backlog.
Transaction Reconstruction
Historical statements help identify activity, but importing them requires care when some transactions already exist. A manually entered payment and a bank download may describe the same event. Likewise, a customer invoice and the payment against that invoice should not become two separate sales.
The review connects related entries and looks for gaps in the sequence. Dates, amounts and supporting descriptions help distinguish genuine duplicate records from separate purchases that happen to have the same amount.
Catch-Up Bookkeeping Example
Illustrative example: a consultant last completed the books in March and needs records through September. The review first confirms March balances, then works through April to September for the relevant checking account, card and payment platform. Missing receipts become a focused list instead of stopping every other transaction from moving forward.
The consultant can then see which months are completed, which entries need an explanation and whether any remaining decision belongs with the tax professional. The scope has a beginning and an end.
Unresolved Transactions
Old purchases are harder to remember, and some records may take time to retrieve. The work should distinguish an unavailable document from a transaction that never occurred. A vendor name alone may not explain the business purpose of a payment, and a statement alone may not establish everything needed for tax support.
Owner explanations can help connect the pieces, but missing evidence should remain visible. The goal is an honest set of records with documented gaps, rather than a report that appears complete because uncertain items were quietly assigned a category.
Use a separate query list for the missing information, with the transaction date, amount and the document or explanation needed. A payment awaiting a receipt should remain distinguishable from an account with an entire statement missing.
Resolve connected activity together. A customer deposit may relate to an invoice entered in another month, while a card payment may settle purchases already recorded. Preserve those links when rebuilding earlier periods.
Current Bookkeeping Records
Catch up and ongoing bookkeeping have different rhythms. While historical periods are being reviewed, saving new receipts and maintaining current account access can keep fresh activity organized. It helps to agree which person is recording new transactions and which person is working on older periods, so their work does not overlap.
At the handoff, the agreed deliverables can include updated ledgers, reconciled periods, refreshed reports and an unresolved item summary. Any timing estimate should reflect the volume of work and the availability of records, rather than a promise based only on the number of months.
The backlog is reviewed in sequence because an unresolved balance from an earlier month can carry into every later month. As periods are completed, the records should identify which accounts have been reconciled and which transactions still need an explanation. That makes progress visible without presenting incomplete historical records as finished.