Income & Expense Tracking
Know where the business income comes from and what it takes to operate. Connect the details so deposits, spending and changing costs tell a more useful story.
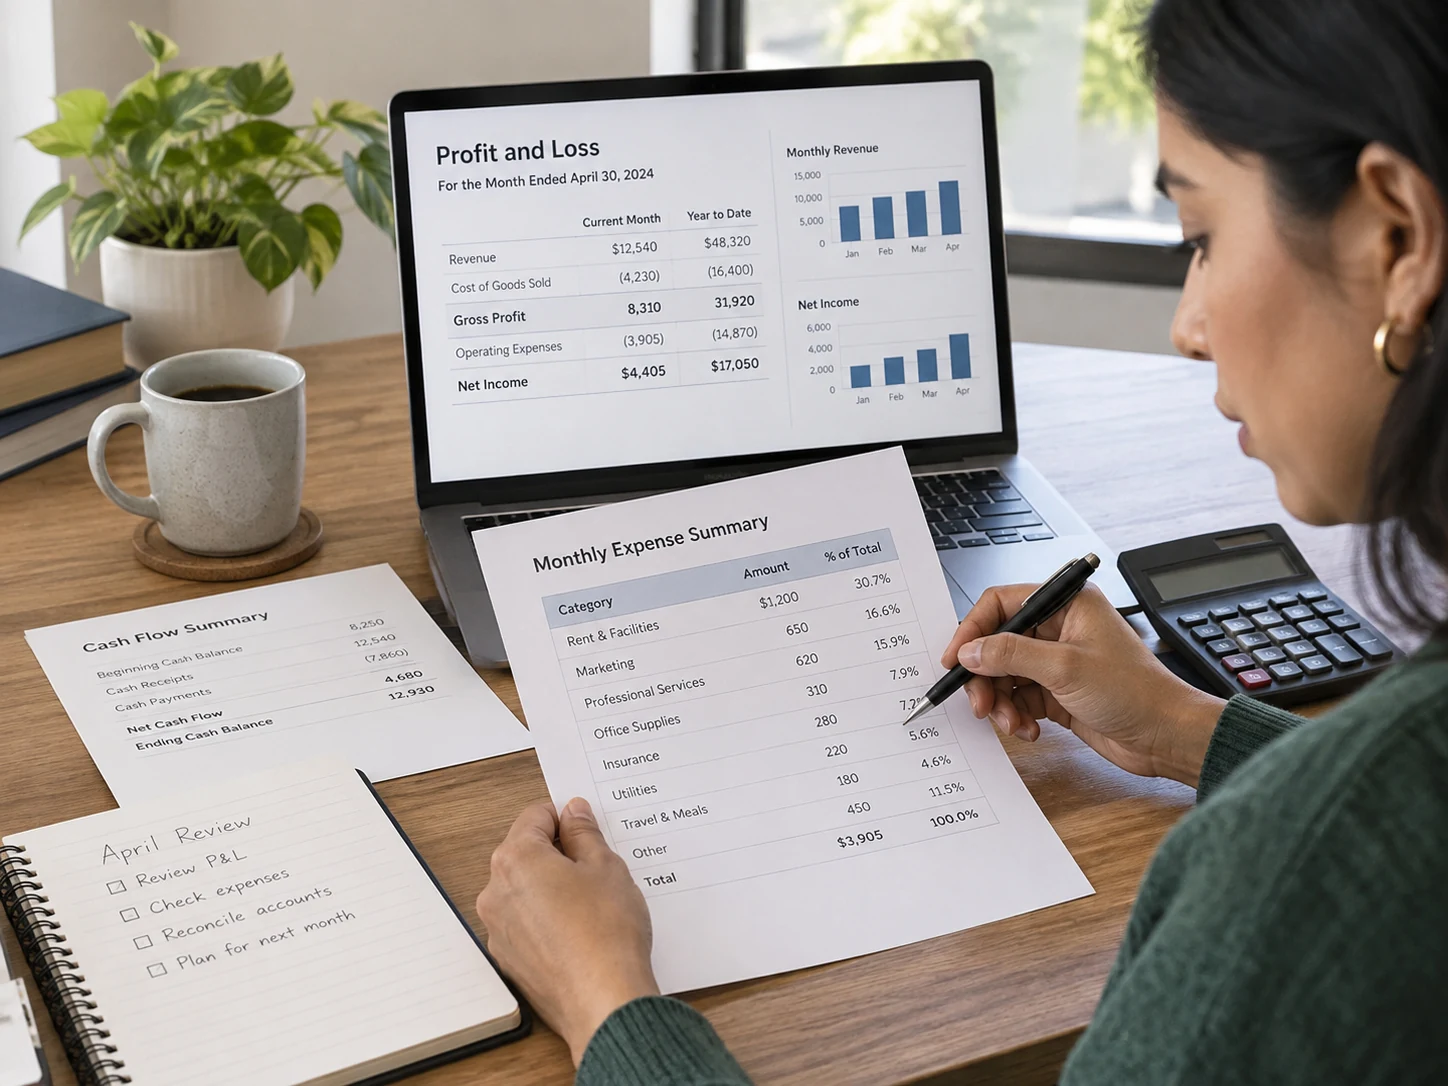
Income & Expense Tracking Scope
Income and expense tracking records business revenue and costs using a consistent approach. It connects payments and purchases to their source information, separates ordinary operations from other money movements and supports comparisons over time. Paper Trail organizes that activity so the owner can see what changed and where a closer look may be useful.
Income & Expense Tracking Services
Income Sources
Customer payments can arrive by card, bank transfer, check, cash or a payment platform. A useful tracking process identifies those channels and makes sure the related activity reaches the books once. Otherwise, a sales system and a bank feed can both record the same customer payment as separate income.
It also distinguishes business sales from other deposits. Funds contributed by an owner, transfers between accounts and loan proceeds can increase cash without representing revenue from customers.
Sales and Deposits
A processor may combine several customer payments into one payout and deduct its fees before the money reaches checking. The deposit is then only part of the story. Refunds, chargebacks and funds still held by the processor can also affect the relationship between sales activity and cash received.
The supporting settlement report helps explain these components. Tracking only the net bank deposit can hide the cost of processing payments and make sales comparisons less useful.
Recurring Expenses
Rent, software, subscriptions, supplies and other operating costs should be recorded in a way that supports comparisons. The review can identify a changed subscription price, an annual renewal or a cost that appears in more than one account. Those observations give the owner something specific to investigate.
The records should still reflect what actually happened. A recurring charge is not automatically unnecessary, and a larger expense is not automatically a mistake. The business context determines whether the change calls for action.
Payment Processor Example
Illustrative example: customers pay $1,000 for completed services and the processor retains a $30 fee before sending $970 to the bank. With no other adjustments in this example, the records need to explain the $1,000 of sales, the $30 fee and the $970 deposit together. Recording only $970 of sales loses part of that picture.
The actual entries depend on the bookkeeping system and existing sales records. The goal is to preserve the relationship without creating a second sale when the payout arrives.
Period Comparisons
A completed calendar month is more meaningful alongside another completed month than alongside a partial period. The same reporting basis and category structure should be used for each comparison. Seasonal activity, annual payments and unusual purchases can help explain why one month looks different.
Cash and profit are also different measures. Borrowing money can improve the bank balance without increasing operating profit, and paying down loan principal can reduce cash without being an ordinary business expense. Looking at the relevant reports together gives those movements context.
Compare the same reporting periods and identify changes in how transactions were recorded. A payment received this month may settle an older invoice, so a change in deposits does not necessarily describe a change in current sales.
Retain a short explanation for significant variations, with the invoice or transaction detail behind it. That gives later reviews a factual starting point without assuming every unusual month will repeat.
Financial Follow-Up
The agreed output can include organized income and expense records, consistent categories and a summary of notable changes or unexplained activity. Supporting reports should make it possible to trace a total back to the transactions that created it. That is more useful than a single number with no explanation.
The first conversation can focus on how customers pay, how many accounts are used and what the owner most wants to understand. Detailed payment records can follow through the appropriate secure process. Keeping the initial description simple helps define the work without asking you to become a bookkeeper first.
A customer invoice, a payment processor report and a bank deposit may describe different parts of the same activity. Paper Trail can review those connections within the agreed scope so income, refunds, fees and receipts remain understandable. The monthly totals then have a supporting trail instead of relying only on amounts that reached the bank.