Accounts Payable & Receivable
Unpaid invoices and supplier bills should be easy to follow. See which balances are current, which are overdue and which need a record corrected before anyone follows up.
Accounts Payable & Receivable Scope
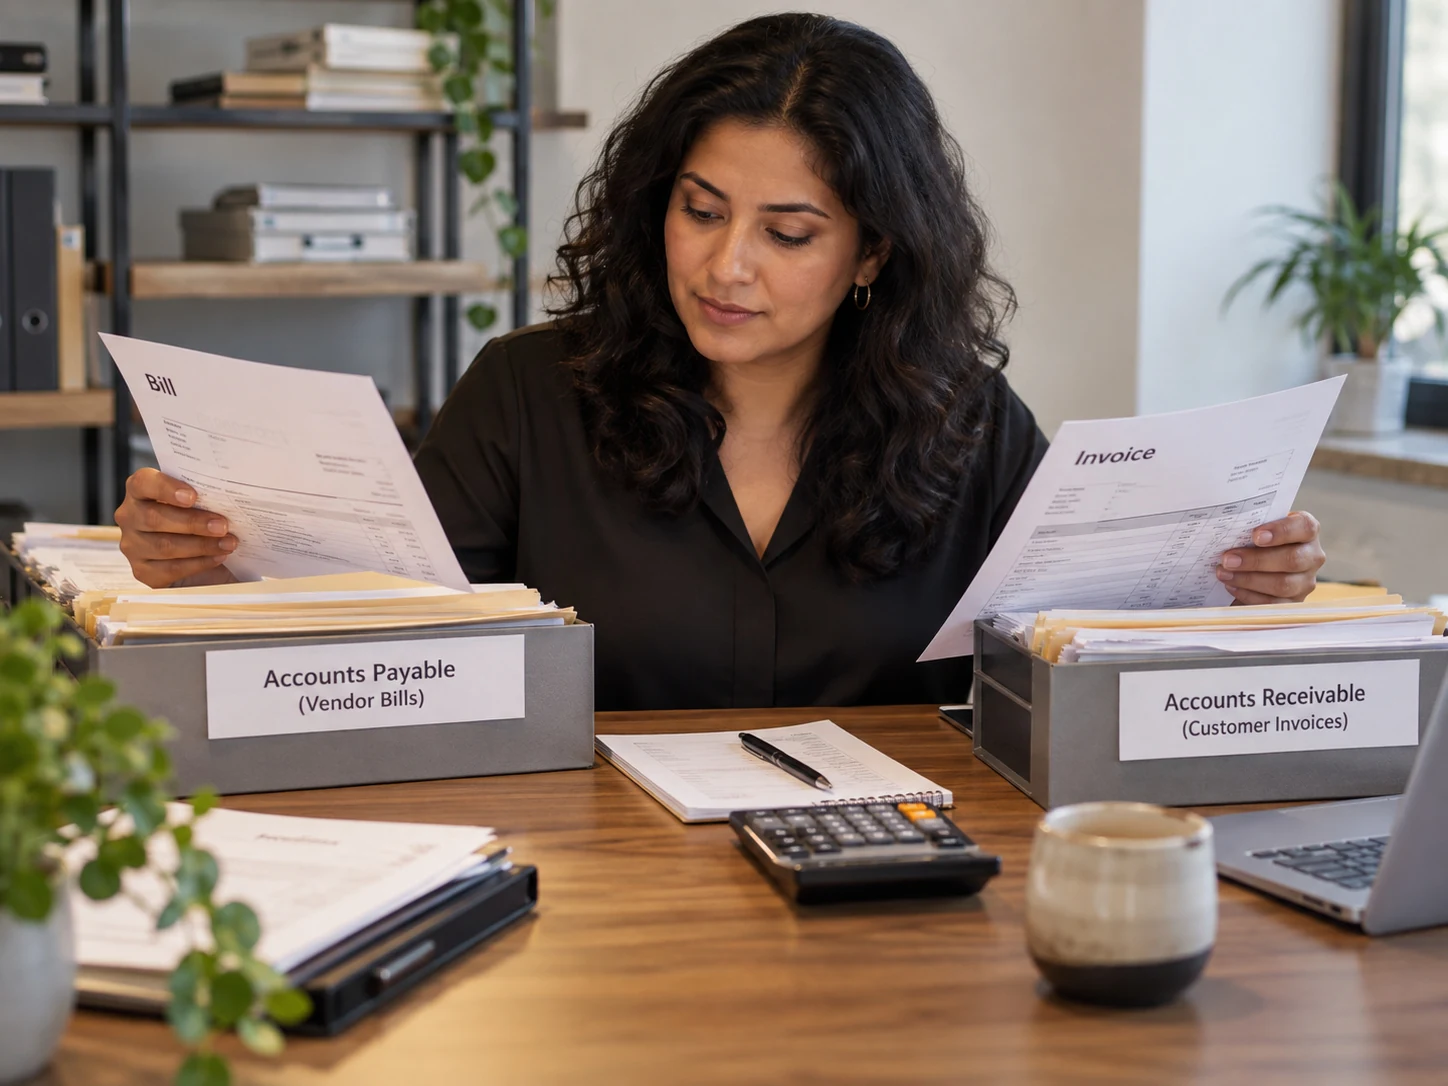
Accounts receivable tracks money customers owe the business. Accounts payable tracks bills the business owes its suppliers. Keeping both records organized helps connect invoices, payments and credits to the right outstanding balance. Paper Trail focuses on maintaining and reviewing those records within the agreed bookkeeping scope.
Accounts Payable & Receivable Services
Invoices and Bills
A useful entry identifies the customer or supplier, document date, due date, amount and reference number. Consistent details help distinguish a new obligation from a copy of something already entered. The supporting document also provides context when a balance is questioned later.
The workflow should establish who issues customer invoices, who enters supplier bills and who approves changes. A record can only stay current if the people involved know where new documents and payment updates belong.
Payment Matching
A customer payment should reduce the invoice it settles. A supplier payment should reduce the related bill when the bill has already been recorded. If the payment is entered separately without making that connection, the original item may appear unpaid even though money has moved.
Partial payments, deposits, credits and overpayments need particular care. Their treatment depends on the underlying agreement and bookkeeping method, so a balance should not be forced to zero without understanding what remains owed.
Aging Reports
An aging report organizes open amounts according to how long they have been outstanding or overdue, depending on the report settings. It helps the business see where follow up may be needed. The dates and payment terms need to be accurate for the report to be useful.
An old balance is a prompt for investigation, not automatic proof that a customer has failed to pay. An unapplied receipt, a missing credit or a duplicated invoice can produce the same appearance.
Partial Payments
Illustrative example: a customer receives a $2,000 invoice and pays $1,200. When the payment is correctly applied, the records show an $800 remaining balance. Recording the $1,200 as unrelated income could leave the invoice showing $2,000 still due and distort the sales record.
The same attention matters for supplier bills. Matching the payment and checking for any credit gives the owner a clearer basis for deciding what actually needs to be paid.
Payment Responsibilities
Bookkeeping records can support customer follow up and supplier payment planning, but maintaining those records does not automatically authorize someone to move funds or contact customers. Any payment approval, invoice sending or collection responsibility should be explicitly agreed.
Disputed balances also need owner input. A refund, write off or credit should reflect an approved business decision and appropriate accounting treatment. Removing an old balance simply because it is inconvenient can hide an unresolved commercial issue.
Keep the approval record with the invoice and payment reference. If an invoice is disputed, record the amount in question and who is resolving it, rather than treating it as approved for payment. Reconcile payment confirmations to the bank statement so an authorized payment, a scheduled payment and a cleared payment remain distinguishable.
Before a payment run, separate invoices approved for payment from items on hold, scheduled automatic withdrawals and credits awaiting application. Include the invoice number, payee, amount and due date in the approval record. The person releasing funds can then distinguish the intended payment from an outstanding bookkeeping entry.
Confirm changes to supplier bank details through an established contact before updating payment instructions. The FBI recommends verifying changes to account numbers and payment procedures. Keep that confirmation with the payment approval.
Open Account Balances
The agreed output can include an updated list of open invoices and bills, applied payments and credits, and clearly identified exceptions. Where receivables and payables are maintained in the ledger, those lists should be reviewed in relation to the corresponding account balances. Differences can signal an entry outside the normal invoice or bill workflow.
For a first conversation, it helps to know whether the larger difficulty is collecting customer payments, keeping supplier bills organized or understanding which balances are real. You can describe those needs without sharing customer identities or individual invoice details in the website conversation.
The bookkeeping record can show the original bill or invoice amount, payments applied, credits recorded and the balance still open at the reporting date. Your business remains responsible for authorizing payments and collection decisions. A current record gives the person handling those decisions a clearer basis for reviewing due dates and following up on outstanding balances.
A larger volume of customer invoices and supplier bills calls for consistent references, payment matching and an organized exception list. Aging reports help distinguish balances that are not yet due from those needing attention. Where several people supply billing or payment information, the handoff should identify who confirms credits, resolves disputed balances and authorizes payment or collection activity.