
Keep Collected Sales Tax Separate From Revenue
Sales tax collected is not always revenue because the treatment depends in part on whether the tax is imposed on the customer or the seller. Taxes imposed on buyers and collected for a taxing authority are generally excluded from income, while taxes imposed on sellers can have different treatment. Keep tax collections identifiable and reconcile them under the rules applicable to the business.
Keep the sale and the tax distinguishable
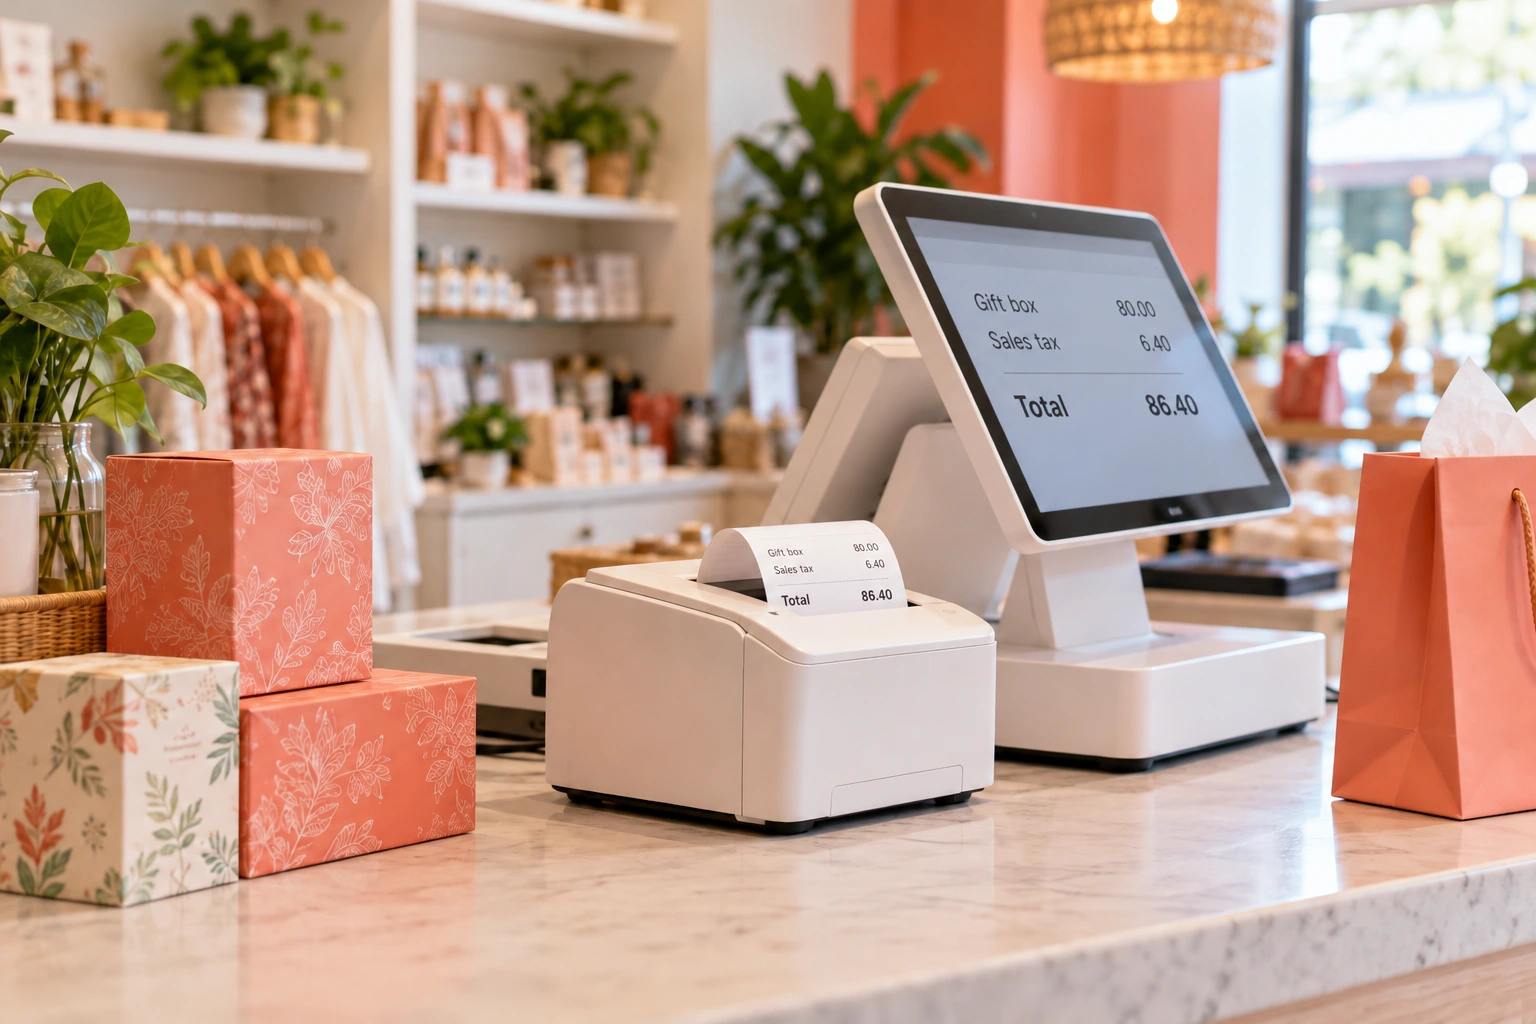
For example, an invoice could contain a service or product charge plus a separately stated tax amount. The customer’s total payment is not enough information to determine revenue. Retain the invoice detail, point of sale reports and tax summaries so the accounting can distinguish the underlying sale from amounts collected for a government agency.
Check the rule for the actual tax
IRS Publication 334 distinguishes taxes imposed on buyers from taxes imposed on sellers. Buyer taxes collected and remitted are generally excluded from income, while taxes imposed on the seller can have different federal income tax treatment. California and other states may have specific rules, so a generic instruction to exclude every amount called sales tax is too broad.
Reconcile collections and remittances
A review compares taxes collected, credits or refunds, amounts paid and any balance remaining. Payments should reduce the relevant liability when that is the accounting treatment, rather than create a second expense. The responsible sales tax professional determines registration, taxability, filing requirements and applicable rates. Bookkeeping supplies organized transaction details and documents the entries so tax collection does not obscure the business’s actual sales performance.