Monthly Bookkeeping Review
Your books hold more than a monthly total. Look at the changes, understand unusual activity and give unresolved items somewhere to go before another month passes.
Monthly Bookkeeping Review Scope
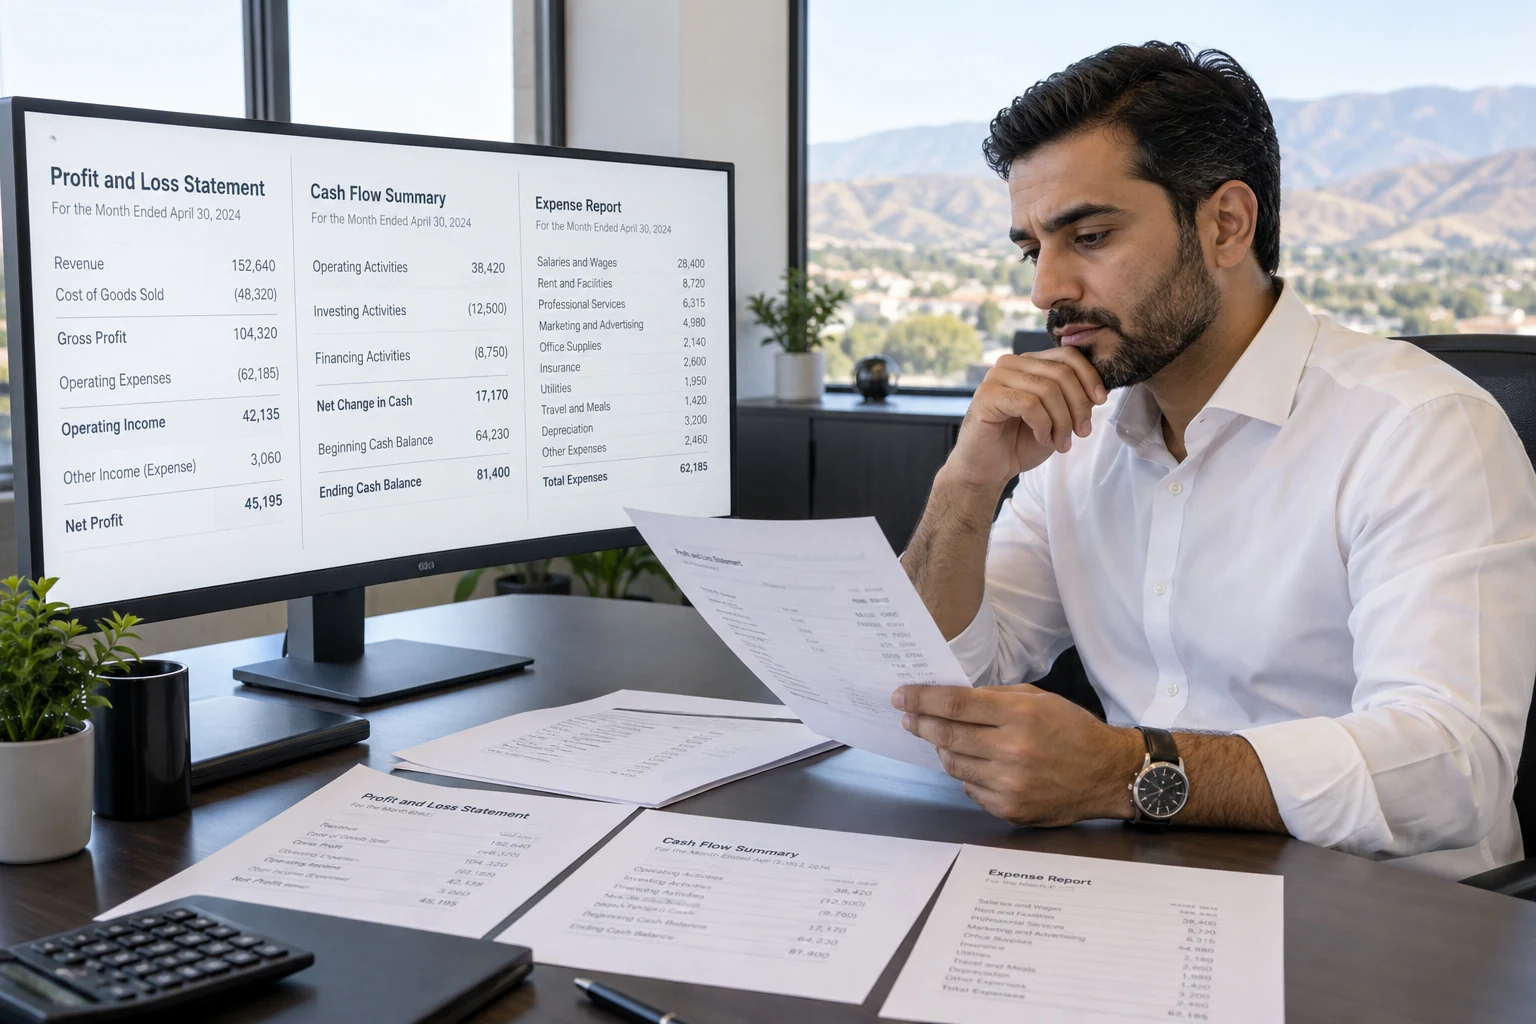
A monthly bookkeeping review is a focused look at completed records and reports. It brings attention to changes in income or spending, unexplained balances and items awaiting owner input. Paper Trail uses the review to connect the bookkeeping with the business events behind it and identify practical follow up.
Monthly Bookkeeping Review Services
Completed Month
The review should identify the period, the reports being used and whether the underlying bookkeeping is complete. If an account statement is missing or a group of transactions remains uncategorized, the discussion should reflect that limitation. A provisional report can be useful, but it should not be mistaken for a finished month.
This service differs from the transaction work itself. Reviewing a report does not replace recording missing activity or reconciling an account that has never been checked.
Account Changes
Not every movement in a report needs a long discussion. A useful review looks for changes that matter to the owner, such as an increase in a recurring cost, a new type of spending or a shift in recorded income. The related transactions can show whether the change reflects ordinary business activity or an error.
The owner supplies context the ledger cannot know. A planned event, a delayed customer payment or a purchase for a new project can explain a pattern that otherwise looks unexpected.
Financial Statements
Unpaid invoices, old supplier balances and loan or card accounts can carry issues that are not obvious from monthly profit. Reviewing these balances helps identify items that may need a document, a payment application or an accountant decision. The point is to make the outstanding work understandable.
Cash changes also deserve context. A month with strong sales can still feel tight if customer payments arrive later, equipment was purchased or debt principal was repaid. The relevant records should be considered together before drawing a conclusion.
Monthly Review Example
Illustrative example: software expense rises from $150 to $450 in a month. Looking at the detail shows a $300 annual renewal alongside the usual subscription. The increase may be correct, and it does not necessarily mean the ongoing monthly cost tripled.
The owner can then decide whether the annual tool still serves the business. If the extra charge instead turns out to be a duplicate entry, the follow up is a bookkeeping correction. The same report change can lead to different actions once the cause is known.
Unresolved Items
A practical review ends with a short, specific record of what still needs attention. Each item should state what is uncertain, what information would help and who can supply it. For example, an unclear purchase might need an owner explanation, while a depreciation question may belong with the accountant.
The following review can check whether the item was resolved. Keeping continuity prevents the same issue from being discussed repeatedly without changing the books or the process behind them.
Give each open item a clear description, the evidence needed and a person responsible for responding. Distinguish a missing invoice from an unmatched payment or a transaction whose business purpose is still unclear.
Carry unresolved items forward with their original references rather than recreating them as a new list each month. When an item is resolved, retain the supporting document and the explanation of the resulting change so the next review can follow the decision.
Review Scope
The best starting point is often the one number the owner most wants to understand. An owner may benefit from a brief review of a few meaningful changes, while a business with several payment channels may need more detail. The scope and format should be agreed around the reports and available records.
A bookkeeping review is not a financial statement audit, tax planning engagement or prediction of future performance. It is a way to understand recorded activity and make the remaining work visible. When a decision needs specialized advice, the review can organize the relevant facts for the appropriate professional.
The review can produce a record of changes discussed, transactions requiring clarification and items assigned for follow up. Keeping that record beside the monthly reports helps prevent the same uncertainty from carrying forward. An issue needing correction, additional documentation or your accountant’s review can be identified separately from work already completed.