
The Receipts That Disappear Before the Year Ends
Published
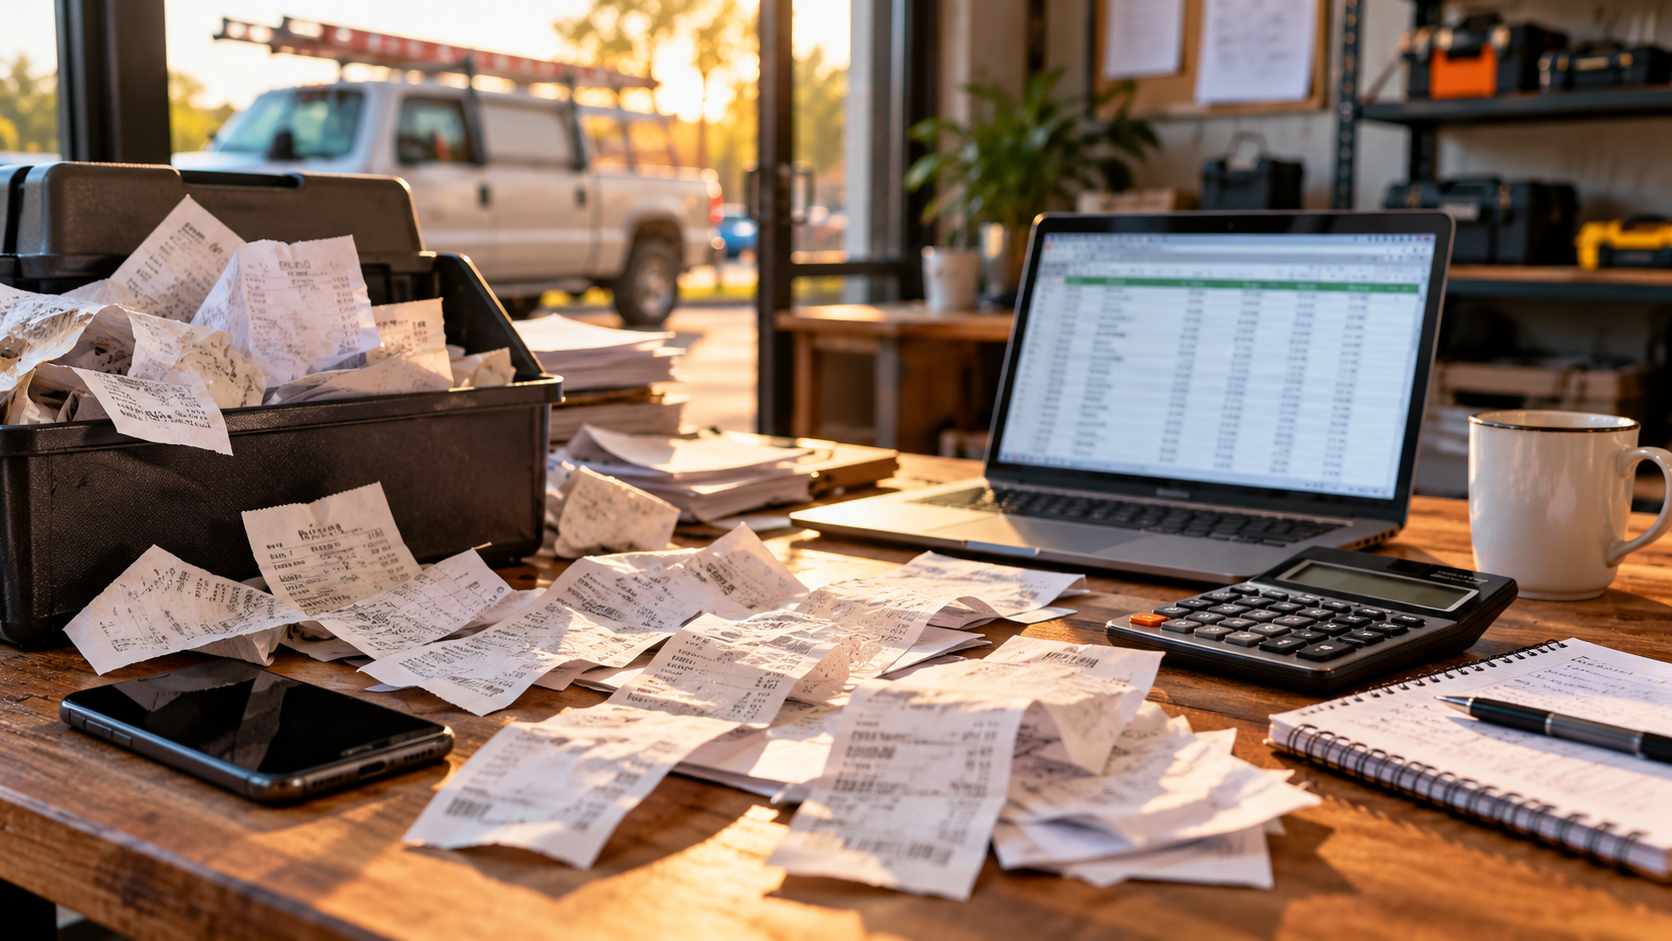
This article is general information about business recordkeeping and is not tax or legal advice for any specific business. It usually starts quietly. A supplier receipt goes into a truck console. A fuel receipt goes into a jacket pocket. A hardware store receipt sits on the dash until the sun turns it pale. An emailed invoice lands in an inbox that nobody opens again. A photo of a receipt sits somewhere in a phone, mixed in with family pictures and screenshots. None of it feels like a problem in March or July. The work got done, the money went out, and everyone moved on. Then the year closes. The books need to match what actually happened. The tax return needs numbers that can stand up. And suddenly those little pieces of paper are the whole story, because without them, a real expense starts to look like a guess.
A bank line is not proof of what you bought
Many owners lean on the bank statement when receipts go missing. The statement shows a date, a store name, and an amount. What it does not show is what was bought. A charge at a supply store could be materials for a job, tools for the crew, or something personal that has nothing to do with the business. A charge at a warehouse store could be cleaning supplies for the office or groceries for a house. The total is there. The meaning is not. The Internal Revenue Service describes purchase and expense records as documents that identify the payee, the amount paid, proof of payment, the date, and a description of the item or service. That description is the part that disappears when the receipt disappears. Without it, the expense has a price tag and no explanation, and an explanation offered from memory months later carries very little weight with a tax preparer, a lender, or an examiner. This is where owners get an unwelcome surprise. They know the purchase was real. They remember the job, the rush, and the reason. None of that memory is a record. The business paid for something it may never be able to prove, and the cost of that gap lands on the business, not on the store that printed the receipt.
Faded paper is the same as missing paper
A large share of everyday receipts are printed on thermal paper, and thermal printing does not age well. Heat, sunlight, friction in a wallet, and time itself turn dark print into a faint shadow, and then into a blank strip. Owners who proudly kept every receipt in a box or a glove compartment open that box in January and find that a third of it can no longer be read. The habit was there. The evidence faded anyway. An unreadable receipt may be inadequate to support a transaction without other documentation. It does not prove the vendor, the date, the amount, or what was purchased. Its value as evidence may be limited, although other contemporaneous records can sometimes help establish the transaction. That is a hard thing to hear after a year of trying to keep paper, but the return does not get credit for effort. It gets credit for records that can still be read when someone asks about them, and the Internal Revenue Service notes that records supporting income, deductions, and credits need to be kept until the period of limitations for that return expires, which is generally three years from filing and longer in some cases. So the fading problem reaches further than one tax season. A receipt that is faint this January may be completely blank by the time a question arrives two years later. The purchase does not change in that time. Only the proof does, and it changes in the wrong direction.
Scattered records turn closing the books into an argument
When proof lives in five or six places at once, closing the year stops being bookkeeping and becomes detective work. One month of expenses is in an email account. Another is in a truck. Card charges belong to two different people, and only one of them remembers what half of them were for. Cash purchases may have no trail at all beyond a scribbled note, if that. Every gap invites a second guess. Was this meal with a client or with family? Was this fuel for a work truck or for a weekend trip? Was this software charge a business subscription or a personal one that shares a similar name? When the answer depends on who is asked and how good their memory is that day, the books stop being a record of the business and become a set of opinions about the business. That matters well beyond tax time. An owner who cannot trust the expense record cannot fully trust the profit it produces. A business can look healthy on paper while real costs sit unrecorded in a drawer, or look weaker than it is because legitimate costs were left out when the proof could not be found. Decisions about hiring, equipment, and taking on new work get made on numbers that everyone quietly knows are soft.
The costs that never make it onto the return
The most painful part of missing receipts is often invisible. Legitimate business expenses that cannot be supported tend to get dropped, softened, or argued over at preparation time. Each dropped expense is money the business actually spent to earn its income, now treated as if it did not happen. The taxable picture gets worse, not because the business earned more, but because it cannot document what it spent. There is also the time cost, and owners feel that one in their bodies. Days in January get burned sorting paper, calling vendors, searching old emails, and trying to rebuild a year that was lived at full speed. Staff get pulled into the hunt. The tax preparer waits, or works around the holes, or charges for the mess. A season that should be about starting the new year becomes a long look backward at a year that was never captured properly while it was happening. And when questions come later, the position is weaker still. The Internal Revenue Service is clear that taxpayers keep the records that support the items on a return, including receipts and other documents that support a deduction or credit. An owner facing a question about an expense with no receipt, a faded receipt, or a receipt that shows a total and nothing else has very little to hand over. The expense may have been completely legitimate. Legitimacy that cannot be shown is a fragile thing. It is rarely an honesty problem. It is a capture problem. Most owners with scattered receipts are not careless with money. They are busy people who bought what the business needed, in the middle of a working day, and treated the paperwork as the least urgent part of the purchase. The receipt problem is not built in one bad moment. It is built in hundreds of small ones, each one reasonable on its own, adding up to a year with holes in it. That is also why willpower alone rarely fixes it for long. January resolve tends to fade by February, right along with the ink. The businesses that do not live this scramble are not the ones whose owners try harder at year end. They are the ones whose records were being kept, completely and legibly, while the year was still happening, by someone whose job that actually is. If opening your own receipt box feels like opening an argument, that feeling is information. The business spent real money all year. It deserves a record that can prove it, long after the ink on a dash receipt has given up. That is the kind of quiet, weekly keeping that Paper Trail exists to carry, so the year closes on records instead of recollections.
Sources and references
- https://www.irs.gov/businesses/small-businesses-self-employed/what-kind-of-records-should-i-keepInternal
- https://www.irs.gov/taxtopics/tc305Internal
- https://www.irs.gov/newsroom/good-recordkeeping-year-round-helps-taxpayers-avoid-tax-time-frustration
- https://www.irs.gov/businesses/small-businesses-self-employed/recordkeeping