
Put Business Transactions in the Right Categories
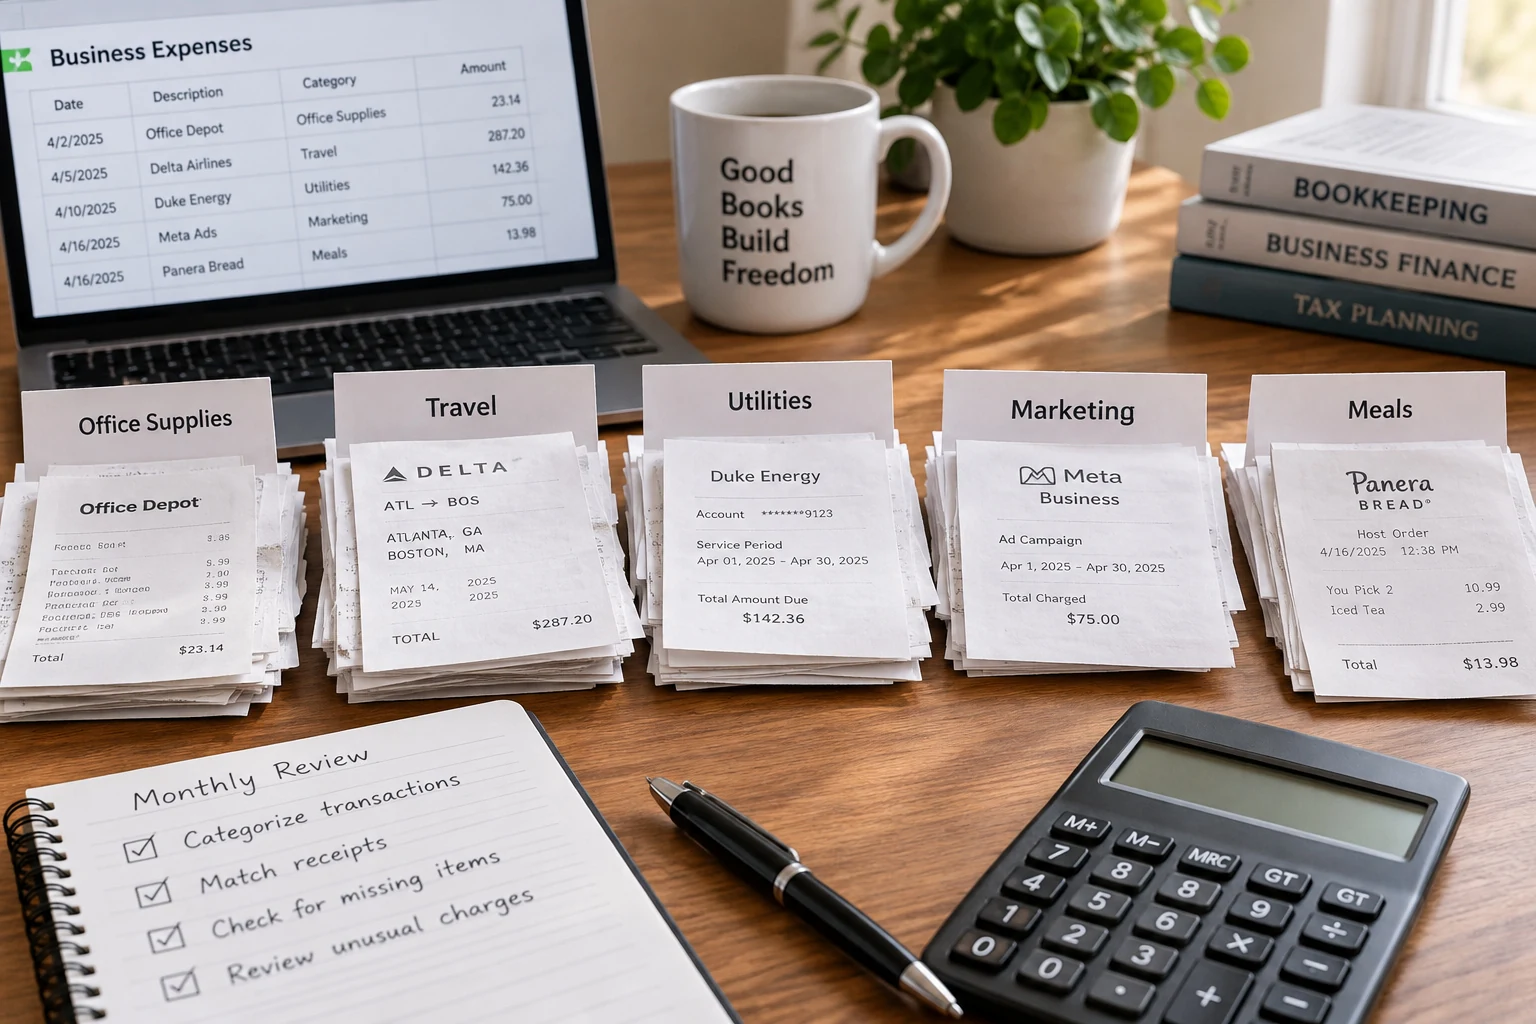
Categorize transactions by what they represent and how they affect the business, using a consistent chart of accounts. First determine whether an item is income, expense, asset, liability, equity or a transfer. Only then choose the more specific category that fits the supporting record.
Read beyond the merchant name
An office retailer may sell supplies, equipment and personal items in the same purchase. A bank deposit may be customer income, borrowed money, an owner contribution or a transfer. Receipts, invoices and transaction explanations help establish the substance. A familiar vendor name is useful context but does not settle every classification.
Keep categories useful and consistent
Use enough detail to understand the business without creating a new account for every vendor. For example, separating materials used on customer jobs from general office supplies can make operating costs more informative. Apply the same policy to similar transactions and document any approved change so comparisons remain meaningful.
Handle uncertainty openly
If a transaction lacks enough detail, place it on a review list rather than guessing. Equipment, mixed personal activity, loan payments and owner transactions often need special attention. Your tax professional may direct treatment for items with tax implications. After corrections, review the affected balances and reports. Good categorization gives a transaction an understandable place in the books while preserving the evidence behind that choice.