
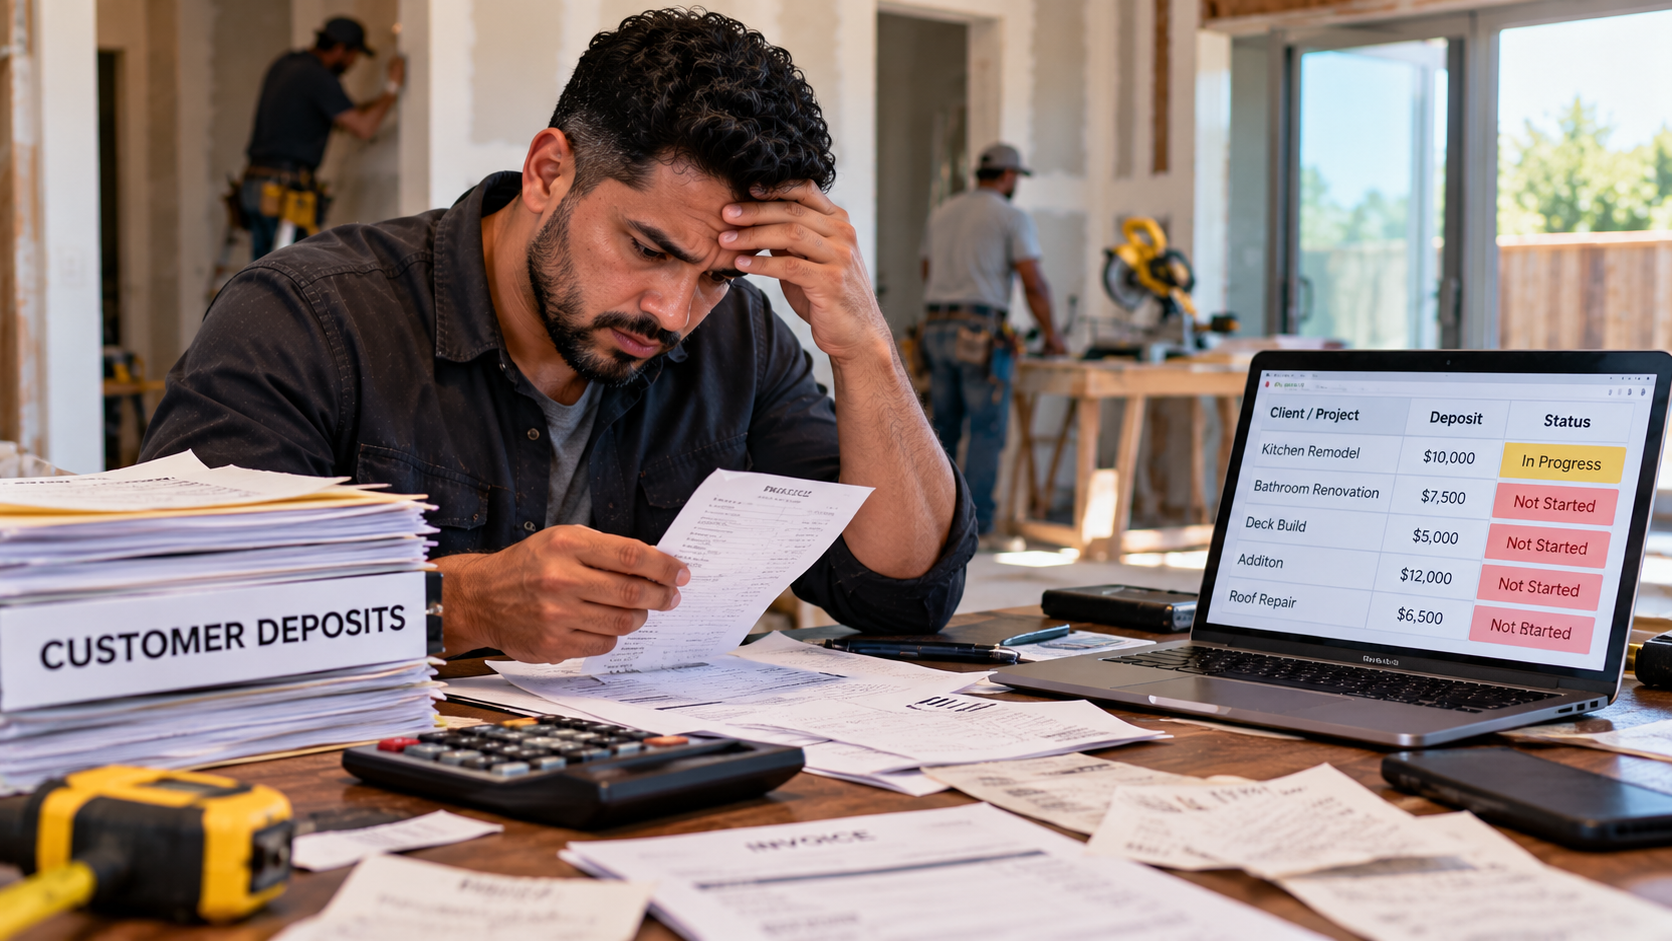
Customer Deposits Were Spent Like Earnings and Now the Work Is Still Owed
Published
This article is general information about business recordkeeping and is not tax or legal advice for any specific business.
A deposit feels like good news. A customer believes in the business enough to pay before the work begins, the bank balance rises, and the business breathes a little easier. For companies that take deposits on future jobs, that money arrives carrying a promise. The work has not happened yet. Materials have not been bought, hours have not been worked, and the customer is trusting that when their turn comes, the business will be ready.
The trouble begins quietly, in ordinary weeks, when deposits and earned money live in the same account and start to look identical. A deposit lands, payroll is due, a supplier needs paying, and the balance looks healthy enough to cover it all. Nothing feels like a decision to spend a customers deposit. It feels like running the business. Months later, the calendar turns, the customer is ready for their job to start, and the business discovers it owes work that the cash no longer stands behind.
Money That Looks Earned but Is Not
Earned money and deposit money tell two completely different stories, even when the dollar amounts are the same. Earned money belongs to the business outright, the reward for work already delivered. A deposit is a customer standing inside the bank account, waiting. It represents hours, materials, and attention the business has committed to provide later, and spending it early does not cancel that commitment. It only removes the cushion that was supposed to make keeping the promise comfortable.
When records do not keep those two kinds of money clearly apart, owners steer by the bank balance, and the bank balance lies by omission. It shows a total, not a truth. A balance that looks strong in a deposit heavy month can hide the fact that much of it is already spoken for by jobs on the calendar. Owners make spending choices, take on new obligations, and judge whether a slow week is a problem, all based on a number that quietly includes other peoples money.
This is rarely dishonesty. Most owners fully intend to do every job they have taken a deposit for. The problem is that intention is not a record. Without records that show, at any moment, how much of the balance is already owed back as work, intention has to carry the whole weight, and intention gets tested every time a bill arrives before a job begins.
The Season When Every Deposit Comes Due
Deposit trouble has a season. Businesses often collect deposits steadily during busy selling months, when enthusiasm is high and the calendar feels far away. Then the schedule matures. Several customers become ready at once. Crews, contractors, inventory, and time all have to be produced in the same few weeks, and each job expects the deposit behind it to help carry its costs. That is when the business learns whether those deposits were preserved as promises or absorbed as everyday cash.
Owners describe the squeeze vividly. New deposits slow down just as old obligations speed up, so there is no fresh cushion arriving to cover the gap. The business finds itself funding promised work out of current income, robbing this months operations to honor last seasons commitments. One delayed customer payment, one unexpected repair, and the chain tightens further, because every dollar now has two jobs to do.
Customers feel the strain without knowing its source. Start dates slip. Communication slows because the owner dreads the conversation. Corners get weighed that should never be weighed. A business that built its reputation on keeping promises can find that reputation wobbling, not because the work got worse, but because the money behind the work was spent long before the work began.
The Conversation No Owner Wants to Have
Eventually, some owners have to talk with a customer about money that should have been waiting. Maybe a job needs to be postponed. Maybe a refund gets requested at the exact moment the account cannot comfortably produce it. Maybe the customer simply asks a direct question about their deposit and watches the owner hesitate. Trust, once it flickers, is hard to restore, and customers talk to neighbors, partners, and review pages.
Refund requests are the sharpest version of the problem. A customer who changes plans is entitled to a clear answer about their money under whatever agreement they signed, and an owner whose deposits have dissolved into general spending faces that request as a crisis rather than a transaction. The business may owe the work or owe the refund, but in cash terms it owes something it no longer has set aside, and every day spent resolving it generates more ill will.
Even when no customer ever complains, the owner carries the knowledge privately. Every glance at the bank balance comes with mental arithmetic, subtracting promises from the total, guessing at what is truly available. That constant, uncertain math follows the owner into pricing decisions, hiring decisions, and sleepless nights before big jobs start. The business looks fine from the outside. Inside, the owner is keeping two sets of books, one in the records and one in their head, and trusting neither completely.
A Pattern That Repeats Until It Cannot
What makes deposit spending so stubborn is that it works, until it does not. For a long stretch, new deposits keep arriving and cover the promises made earlier, and the business mistakes that flow for health. Growth can mask it for a while, because a growing business always has fresh money coming
in. The mask slips the moment growth pauses, a season slows, or several large jobs land at once. Then the business discovers that its model quietly depended on tomorrows customers funding yesterdays promises.
That discovery often arrives alongside other pressures. Taxes come due on income the records treated loosely. An accountant asks questions the owner cannot answer cleanly about which deposits were earned and which are still owed. A lender or partner looking at the books sees revenue that does not match work performed and starts asking harder questions. A problem that began as a blurry bank balance becomes a problem of credibility, with the owner explaining a pattern that sounds worse the longer it went unnoticed.
Owners who reach this point are seldom careless people. They are busy people whose records never drew the one line their business model depends on, the line between money earned and money held in trust for work ahead. Without that line drawn clearly and kept current, every deposit season plants the seeds of a future squeeze, and the business relives the same stressful cycle with larger numbers each year.
The Work Is Still Owed
Strip away the accounting language and the situation is simple enough for anyone to feel. Customers paid early because they trusted the business to show up later, ready and able. The business accepted that trust in the form of cash, spent the cash as if the story were already finished, and now faces the middle of the story with an empty hand. The work is still owed. The promises are still on the calendar. Only the cushion is gone.
That is why this problem haunts owners more than many larger mistakes. It is not about a bill or a balance. It is about standing in front of good customers, people who paid in good faith, and knowing the business made their jobs harder to deliver through no fault of theirs. Owners who have lived it tend to say the same thing, they never want to look at a bank balance again and wonder how much of it is really theirs. Until the records answer that question clearly, every deposit that lands is both a compliment and a risk, and the calendar keeps turning toward the days when the promises come due.
Sources: https://www.irs.gov/businesses/small-businesses-self-employed/recordkeeping, https://www.sba.gov/business-guide/manage-your-business/manage-your-finances, https://www.sba.gov/business-guide/manage-your-business/stay-legally-compliant
Paper Trail | Online Bookkeeping | 818-934-0444