
Catch Up Bookkeeping: Bring Months of Overdue Books Up to Date
Published
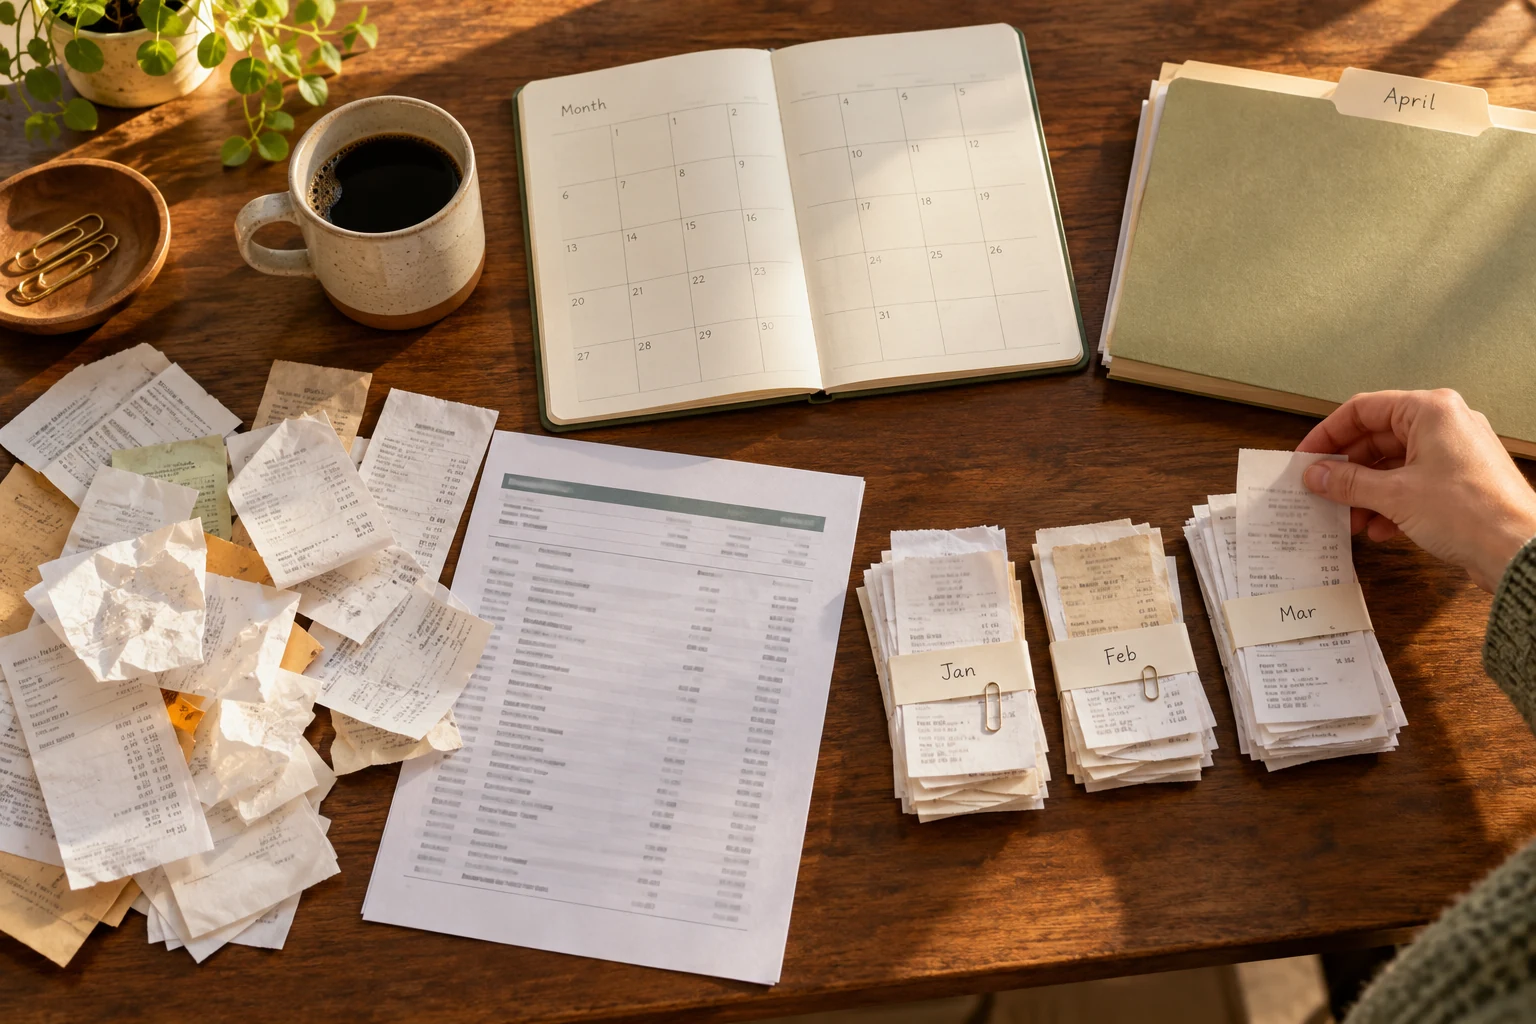
Catch up bookkeeping brings overdue business records up to date by organizing transactions, reconciling accounts and resolving missing or incorrect entries. The work starts with a defined time period and the records for every account used during that period. The goal is a reliable set of books and a routine that prevents the same backlog from returning.
A backlog often starts with a busy month
You finish the client work, pay the most urgent bills and promise yourself you will sort the records over the weekend. Then another week fills up. Eventually, opening the accounting software feels like starting a project instead of checking on the business.
The useful starting point is a clear boundary. Identify the last month you know was reviewed, then list the months that still need attention. A backlog of unrecorded transactions calls for different work from a file that contains transactions but has incorrect balances. Naming the actual problem makes the repair easier to organize.
Bring the records together before changing entries
Make a list of the bank accounts, credit cards and payment services the business used during the period. Include accounts that were closed or replaced. Gather statements for each month, then collect the invoices, receipts and other documents that explain the activity.
The IRS explains that supporting documents provide the details behind entries in business books. A bank statement may show that money moved, while an invoice or receipt helps explain the purchase. Keeping both gives the review something firmer to work from than a payee name you no longer recognize.
Follow the activity one month at a time
Reviewing a whole year as one large pile makes it harder to see where a difference began. A monthly sequence creates a clearer trail. Confirm the starting point, review the transactions for that period and compare the recorded activity with the corresponding statements.
Transfers and credit card payments deserve particular attention. Moving money between business accounts does not create a new sale. Paying a card balance is also different from recording the individual purchases on that card. Treating these movements as ordinary income or expenses can distort the reports even when the bank total looks familiar.
Keep missing details visible
Some entries will need more explanation. A payment might have a vague description, a receipt may be missing or a deposit might combine several customer payments. Keep a short list with the date, amount, account and the detail still needed. This is more useful than repeatedly reviewing the same uncertainty without recording what you found.
For example, imagine three similar charges from one supplier. The statement alone may not explain whether they were separate orders, a duplicate payment or a charge followed by a refund. Comparing the supplier records with the payments helps resolve the situation without guessing or deleting an entry simply to make the difference disappear.
Review the results beyond the bank balance
A completed reconciliation is an important part of the work, but it does not explain every business decision. Review the resulting income and expense categories, unpaid customer invoices, vendor bills and relevant account balances. A transaction can appear in the right bank account while still being recorded in the wrong category.
The purpose of reliable records extends beyond filing taxes. The IRS notes that good records support financial statements and help owners monitor their business. After a cleanup, the reports should be easier to connect with the work you remember, including unusual purchases, quiet months and periods with higher sales.
Make the finished month easier to repeat
The strongest result is a reviewed set of records plus a manageable routine. Keep a clear list of completed months and anything still awaiting information. Store the supporting documents so the person reviewing next month can find the relevant period without starting a new search.
A small recurring handoff can reduce the work that accumulates between reviews. It might include newly received statements, receipts that need an explanation and changes to business accounts. The routine should fit the way the business operates. Catching up becomes more valuable when the next month builds on the completed work instead of recreating the same backlog.
Catch up work and cleanup can overlap
Catch up bookkeeping completes missing periods. Bookkeeping cleanup corrects recorded activity that is duplicated, misclassified, unsupported or unreconciled. A business can need both services at the same time. The distinction matters because a file containing thousands of downloaded entries may still require more investigation than a file with fewer transactions that were never entered.
A useful scope names the periods, accounts and outputs involved. It also explains how missing documents and unresolved balances will be handled. The number of months gives part of the picture, while the condition of the opening balances and supporting records explains the rest. Current monthly bookkeeping can then begin from the supported historical work.